What ESG Means For The Things You Buy
From food and fashion to banking and household products, sustainability claims are becoming harder for companies to make without evidence. Here is what ESG means, how the rules differ between countries and what consumers are actually likely to notice.
When we shop today, we no longer make decisions based only on price and taste. Many of us want to know where a product comes from, how it was made, and how a company deals with energy, water, packaging, employees or suppliers.
So, What Does ESG Actually Mean?
This is exactly where ESG comes in. ESG stands for Environmental, Social and Governance: environmental responsibility, social responsibility and responsible corporate governance. Companies must disclose, under certain EU requirements, how they deal with environmental impacts, social standards and the responsibilities of management.
Much of this is not new. But for organic businesses, the question is how existing standards, certifications and established sustainability practices can be translated into these new reporting systems. It is therefore not surprising that many companies see one thing above all: bureaucracy.
The EU has gradually built ESG requirements into a legal framework that can sometimes exceed what is practically manageable, and many companies are simply overwhelmed by extensive and continuously expanding requirements.
New rules require additional staff, and ultimately consumers may have to bear the cost. Austria once again shows that it is a master of so-called gold-plating, the meticulous over-implementation of EU legislation. Many businesses were already exemplary in environmental protection and sustainability before these rules and are now being asked to go even further.
The Rules Behind The Acronym
Strictly speaking, there is no single “ESG regulation”. It is better understood as an assessment and organisational framework used by banks, investors, public-sector clients, companies elsewhere in the value chain and ultimately consumers to understand how sustainably, resiliently and future-ready a business operates.
The term ESG is therefore used as an umbrella concept. In reality, the regulatory framework consists of several components. One of the most important is the Corporate Sustainability Reporting Directive, or CSRD, which governs sustainability reporting by large companies.
Companies affected by the reporting obligation must regularly disclose which sustainability risks they face and how these risks affect them. An important principle is so-called double materiality.
Companies do not report only on how climate change, resource scarcity or social developments affect their business model. They must also disclose the impact they themselves have on the environment and society.
The ESRS, or European Sustainability Reporting Standards, define in more detail what must be reported under the CSRD and how. They specify which metrics, strategies, targets, risks, measures and processes must be disclosed.
These include information on climate targets, emissions, energy use, employees, supply chains, biodiversity and corporate governance. The ESRS are currently being revised, with the broader EU simplification process intended to reduce the administrative burden.
For smaller and medium-sized companies, there is also the voluntary VSME standard, the Voluntary Sustainability Reporting Standard. It requires significantly less effort while still helping companies provide structured and credible information.
This is particularly important for SMEs because many are affected indirectly. Even if they are not themselves required to report, they may be part of the supply chain of a larger company. In that case, they may be asked about energy use, emissions, labour standards, the origin of raw materials or compliance. The voluntary standard is intended to prevent every large company from sending its own questionnaire and overwhelming SMEs with different requirements.
How The Rules Change Around The World
The EU has developed one of the broadest sustainability-reporting regimes, but companies in the UK, Switzerland, the United States and Australia also face sustainability and climate-disclosure requirements. The important difference is that these systems do not all define ESG in the same way.
United Kingdom
The UK no longer follows EU sustainability legislation automatically after Brexit, but it is developing its own reporting framework. In February 2026, the government published UK Sustainability Reporting Standards S1 and S2, based closely on the international ISSB standards. S1 covers sustainability-related financial risks and opportunities more broadly, while S2 focuses specifically on climate.
From accounting periods beginning on 1 January 2027, UK-listed companies will be required by the Financial Conduct Authority to report against these standards on a “comply or explain” basis. The UK approach is therefore somewhat different from the EU model. It places stronger emphasis on information that is financially relevant to investors rather than the EU’s broader double-materiality concept.
The UK also has specific Sustainability Disclosure Requirements for investment products, including rules on sustainability-related labels, naming and marketing. These are intended in part to reduce greenwashing in financial products.
Switzerland
Switzerland has its own sustainability-reporting regime rather than adopting EU law directly. Large public companies and financial institutions are already required under the Swiss Code of Obligations to report on environmental and employee matters, human rights and anti-corruption measures. Companies must describe their principal risks, policies and how effective those policies are.
Switzerland also introduced an Ordinance on Climate Disclosures in 2024. The Federal Council has, however, paused planned revisions while it considers a more pragmatic approach and watches how EU sustainability regulation develops.
For Swiss companies, the EU nevertheless remains highly relevant. A Swiss business may fall under European requirements directly because of its activities in the EU or indirectly because a large European customer asks suppliers for sustainability information.
In practice, this means that a Swiss SME may never be directly covered by the CSRD but can still receive detailed questions about emissions, energy, sourcing or working conditions from customers further up the supply chain.
United States
The US picture is much more fragmented. There is currently no single nationwide ESG-reporting regime comparable with the EU’s CSRD. At federal level, the Securities and Exchange Commission adopted climate-disclosure rules in 2024, but their implementation was stayed during litigation. In May 2026, the SEC proposed rescinding those rules entirely.
That does not mean sustainability reporting has disappeared in the US. Individual states can impose their own requirements. California, for example, has introduced major corporate climate-disclosure legislation.
US-based companies doing business in California with annual revenue above $1 billion are required to report Scope 1 and Scope 2 greenhouse-gas emissions beginning in 2026, with Scope 3 reporting following from 2027. Another California requirement covers climate-related financial-risk reporting for businesses with more than $500 million in annual revenue.
The result is a more fragmented system than in Europe: federal securities regulation, state rules, investor expectations and voluntary reporting standards can all overlap.
Australia
Australia has moved decisively towards mandatory climate reporting. Its new climate-related financial-reporting regime began on 1 January 2025 and is being phased in across different groups of large companies and financial institutions through 2027.
Companies within scope must prepare a sustainability report containing climate-related financial information under the Australian standard AASB S2. This includes material climate risks and opportunities, greenhouse-gas emissions, governance, strategy, risk management, targets and climate-scenario analysis.
Unlike the broader European ESG regime, Australia has initially concentrated mandatory sustainability reporting specifically on climate-related financial information.
The rules are also designed mainly for larger companies and financial institutions. Smaller companies may nevertheless be affected indirectly when large customers request information from their supply chains.
Same Idea, Different Standards
The direction of travel is similar across these markets, but the regulatory logic differs. The EU has built the broadest framework and looks both at how sustainability issues affect a company and at the company’s impact on society and the environment.
The UK is moving towards ISSB-based reporting with a stronger investor and financial-materiality focus. Switzerland has mandatory non-financial and climate reporting for certain large companies but is taking a comparatively pragmatic approach to further expansion. The United States remains fragmented, with weaker federal requirements but significant state-level regulation in places such as California. Australia has introduced mandatory reporting but has initially concentrated on climate-related financial risks and opportunities.
For businesses operating internationally, this creates a practical challenge: ESG is increasingly global, but the information a company has to collect and disclose still depends heavily on where it operates, where it is listed and who its customers are.
Does Any Of This Actually Make A Difference?
One advantage of the many regulations is that sustainability performance becomes more comparable and activities can be supported by traceable data. This should also make risks more visible and allow companies to respond earlier and more precisely.
It should also make greenwashing more difficult. The more sustainability information is standardised, documented and verifiable, the harder it becomes to make advertising claims that are not backed by figures and facts. Reporting obligations create more transparency, but they do not solve environmental or social problems.
A company can report extensively and still make only slow progress in implementation. Conversely, smaller organic, food or craft businesses may maintain very high standards but lack the capacity to turn them into readable reports.
Consumers should be better able to assess whether a company genuinely takes responsibility for the use of resources, climate protection, fair working conditions, supply chains, animal welfare, packaging or corporate governance.
At a time when many products are marketed as “sustainable”, “climate-friendly” or “responsible”, structured ESG information can help. It creates a framework in which companies have to substantiate their claims rather than simply state that they are doing something “good”.
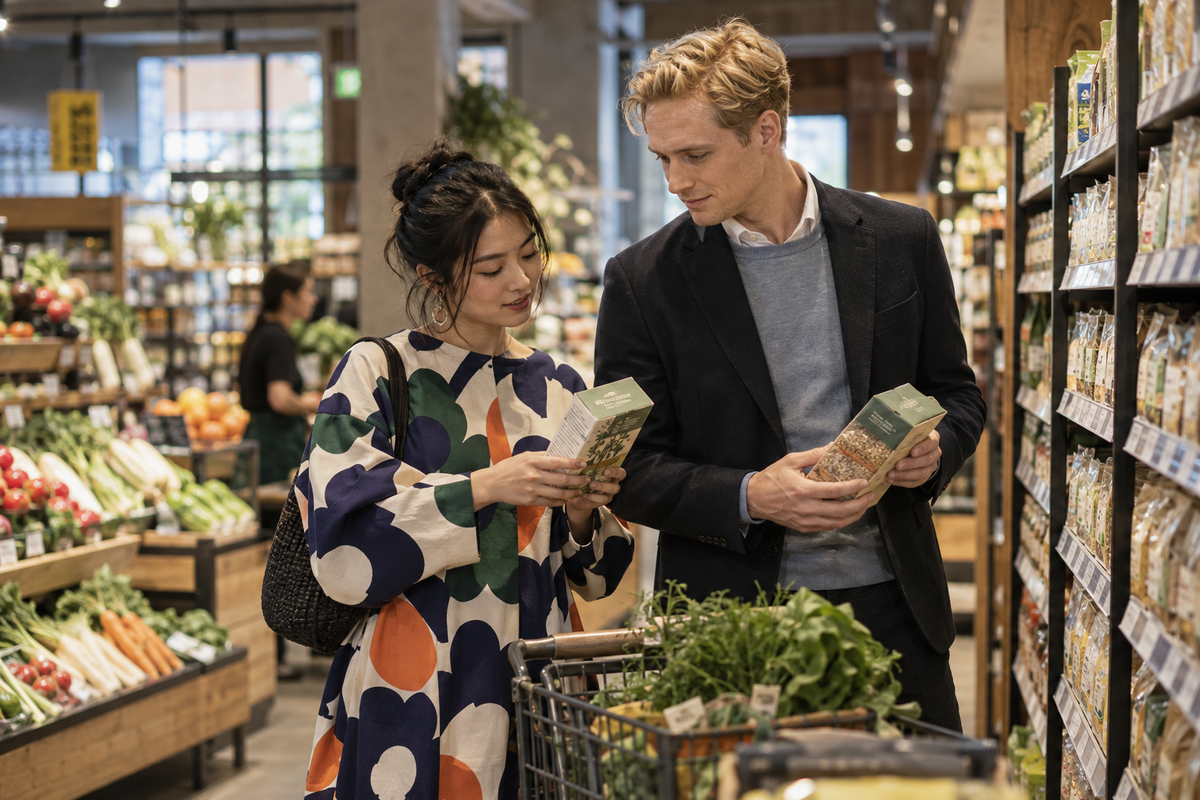
In practice, however, very few consumers will regularly compare sustainability reports, CSRD disclosures or ESG metrics. Someone shopping locally, for example in an organic shop, at a farmers’ market, in a bakery, from a direct producer or from a local food business, is more likely to make decisions based on trust, experience, proximity and personal conviction than on lengthy reports.
For consumers, the real value lies less in reading the reports themselves and more in giving companies, retailers, banks, certification bodies, media and regulators a better basis for assessment and oversight.
When ESG is implemented well, it can strengthen trust, make abuse more difficult and make credible providers more visible, especially in areas where consumers have little direct insight.
For regional and sustainably managed businesses, the key is to ensure that reporting obligations do not simply create another burden but make their real performance visible.
Short, understandable information, credible origin and a direct connection to the product are often more valuable than any extensive sustainability table.
What It Means For The Claims You See While Shopping
The EU Directive on Empowering Consumers for the Green Transition, known as the Empowering Consumers Directive or EmpCo, forms part of the EU Green Deal framework.
Its aim is to better protect consumers from misleading sustainability claims and unclear environmental labels.
In concrete terms, companies will no longer be allowed to advertise using broad claims such as “environmentally friendly”, “green”, “climate neutral”, “sustainable” or “ecological” without a clear and verifiable basis showing what those terms actually mean.
Consumers should also receive more information about how durable and repairable a product is, whether spare parts are available and how long software updates will be provided.
Sustainability labels will also be more tightly regulated. Self-created fantasy labels or poorly transparent quality marks should no longer be accepted as credible evidence of sustainability.
The directive was adopted in 2024. Member states were required to transpose it into national law by March 2026. The rules apply from September 2026. Many European countries are not implementing the directive through a single new “greenwashing law”, but by amending existing legislation. One objective is to provide consumers with better information before purchase about durability, repairability and certain sustainability characteristics.
Where The Grey Areas Remain
Regulation creates more transparency, but it also creates new grey areas. Companies can disclose a great deal and still communicate selectively. If complex sustainability data is reduced to a few marketing messages, it can still create a distorted picture.
Sustainability is also difficult to capture in a single metric. A product may perform well on climate impact but less well on water use, packaging or social standards.
“Improvement” is also not the same thing as “sustainable”. This distinction may have to be disclosed in a sustainability report, but how understandable it remains for consumers is another question. This is where grey areas emerge, because a complex reality is difficult to compress into standardised reports. Companies are also operating in an economically challenging environment. Prices are rising and every additional cost eventually has to be reflected somewhere. For this reason, the European Commission proposed its so-called Omnibus package to simplify reporting obligations. The start of certain requirements has been postponed, and reporting obligations to different authorities are intended to be consolidated. For smaller organic businesses in particular, these developments cut both ways. On the one hand, many already work to standards that enjoy a high degree of public trust, such as controlled origin, documented production methods, traceability or animal-welfare criteria.
On the other hand, organic certification is not automatically the same as ESG. It is another standard again. While “organic” mainly describes production methods, animal husbandry or control systems, ESG goes much further. It asks for energy and climate data, supply-chain information, working conditions, diversity, governance, risk management and strategic targets. An organic business can therefore operate very credibly and sustainably in its core activities and still find that new reporting obligations ask very different questions from traditional organic certification. Conversely, a company can produce ESG reports without automatically being “organic”.
ESG At A Glance
Environmental covers climate protection, energy consumption, greenhouse-gas emissions, water, biodiversity, waste and the circular economy.
Social covers working conditions, health and safety, equal treatment, human rights, supply-chain responsibility and consumer protection.
Governance covers business ethics, compliance, anti-corruption measures, transparency, control systems and sustainable corporate strategy.

